Glassnode Alpha Lab
Alpha Lab helps investors turn Glassnode’s on-chain and market data into transparent, testable trading heuristics without having to build a research pipeline from scratch.

Crypto investors have access to more data than ever. On-chain activity, exchange flows, derivatives positioning, spot markets, order books and network fundamentals can each reveal a different part of the market.
That breadth is one of Glassnode’s greatest strengths. It can also create a difficult first question: Where should I start?
When a catalogue contains thousands of metrics, finding the small set that matters for a specific investment decision can become a research project of its own. Experienced quantitative teams can build pipelines to test combinations, transformations and thresholds. For many investors, however, moving from a chart in Studio to a systematic decision rule still requires too much time, code and specialist knowledge.
We built Glassnode Alpha Lab to close that gap.
Alpha Lab is a quantitative research platform that searches Glassnode’s data for simple, human-readable trading heuristics. Tell the application what you want to identify, choose the market data you want to investigate, and the research engine tests which combinations have historically been most useful.
The goal is straightforward: turn a large metric universe into a focused set of ideas that an investor can understand, challenge and incorporate into their own research process.
Start with the investment question
Which Glassnode metrics have historically helped identify good buying opportunities in Bitcoin?
From there, the user chooses the metrics the platform should explore, from on-chain and spot data to futures, options and order-book signals, and decides what the search should prioritize. This could be stronger risk-adjusted returns, measured through the Sharpe ratio, or greater absolute performance.
The question sets the asset and the objective; the labeling defines the truth. Every day in the available history is marked as a good buying opportunity or not, based on what the market actually did next. Each selected metric is then expanded into many transformed versions of itself, and the task becomes a simple statistical one: which of those readings were present on the good days and absent on the rest?
Decision trees are built to answer exactly that: every branch is a threshold that separates the good days from the rest. Hundreds are grown together, with an optimizer continually adjusting how they are built. Every attempt is scored the way a trader would score it: on how the resulting strategy would have performed.
The engine then extracts the strongest findings as heuristics rather than returning a black-box prediction. Because each tree is kept deliberately shallow, every path through it that ends in a "yes" is already a concise rule: one or two metric conditions describing a zone where good days clustered. Each zone is then judged on how often it was right and on how much history it rests on.
A result might take the form of:
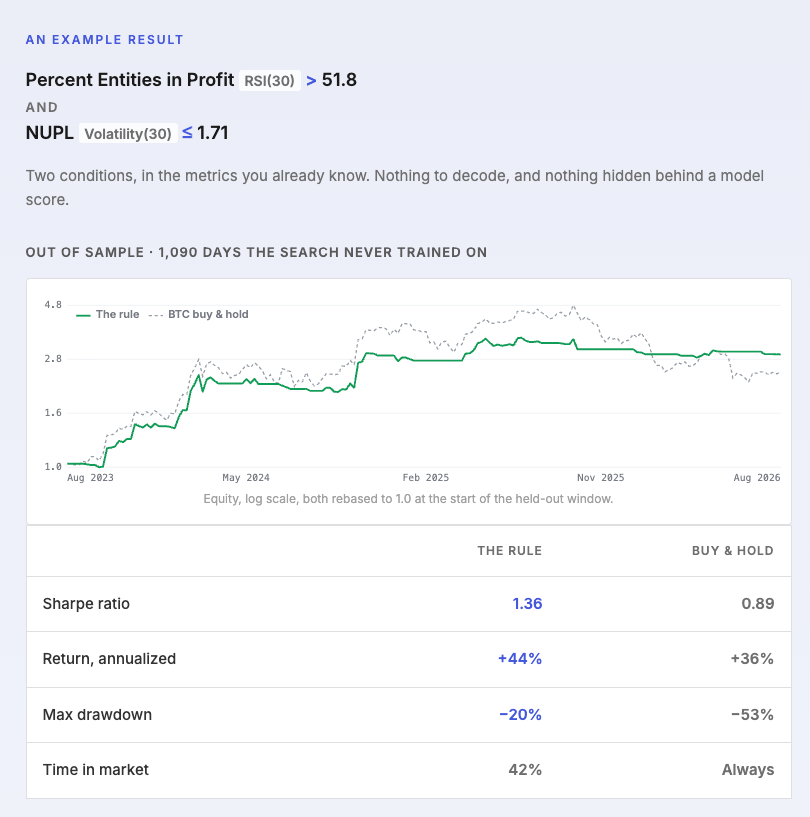
“When this transformed metric is below X, and this transformed metric is above Y, this is the prime area to improve risk-adjusted return on BTC”
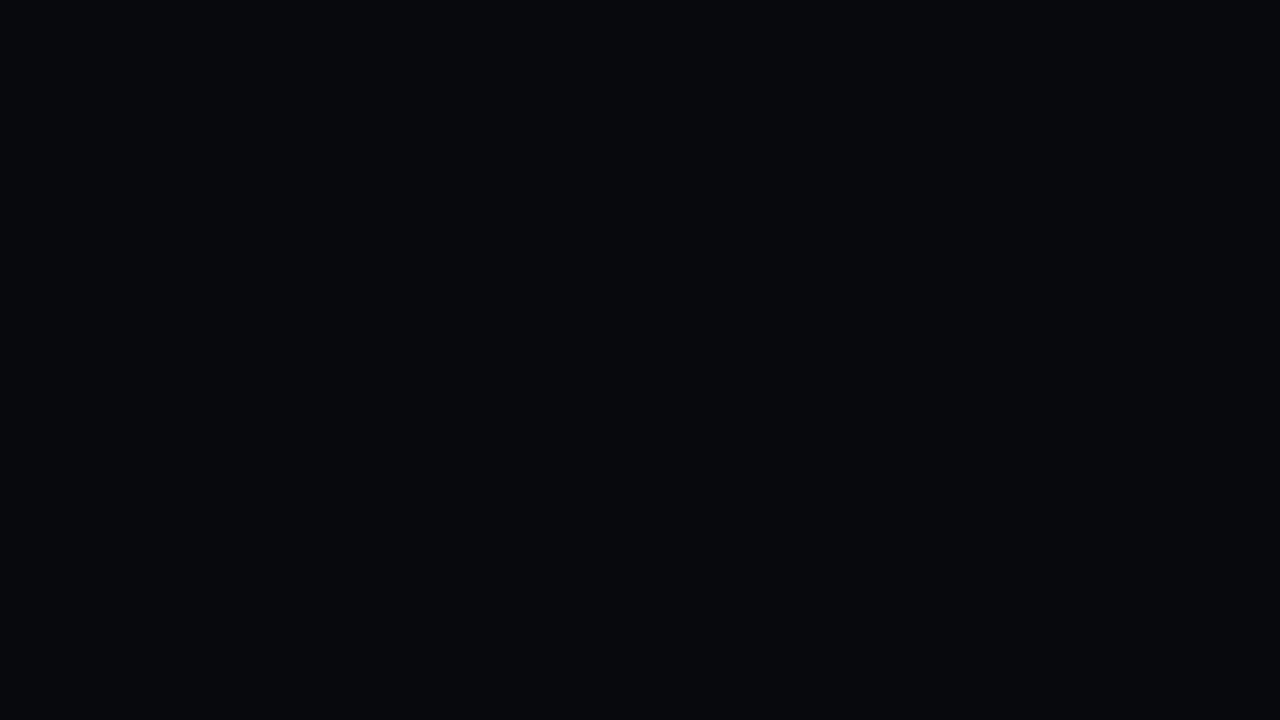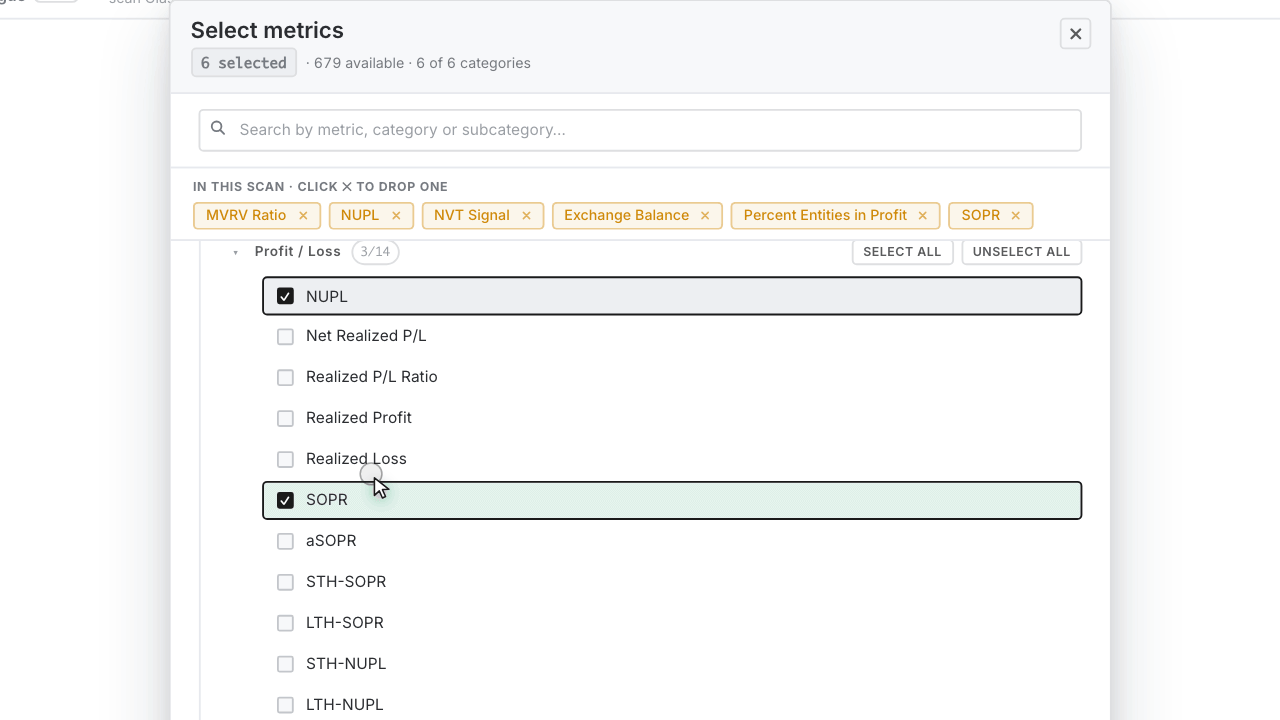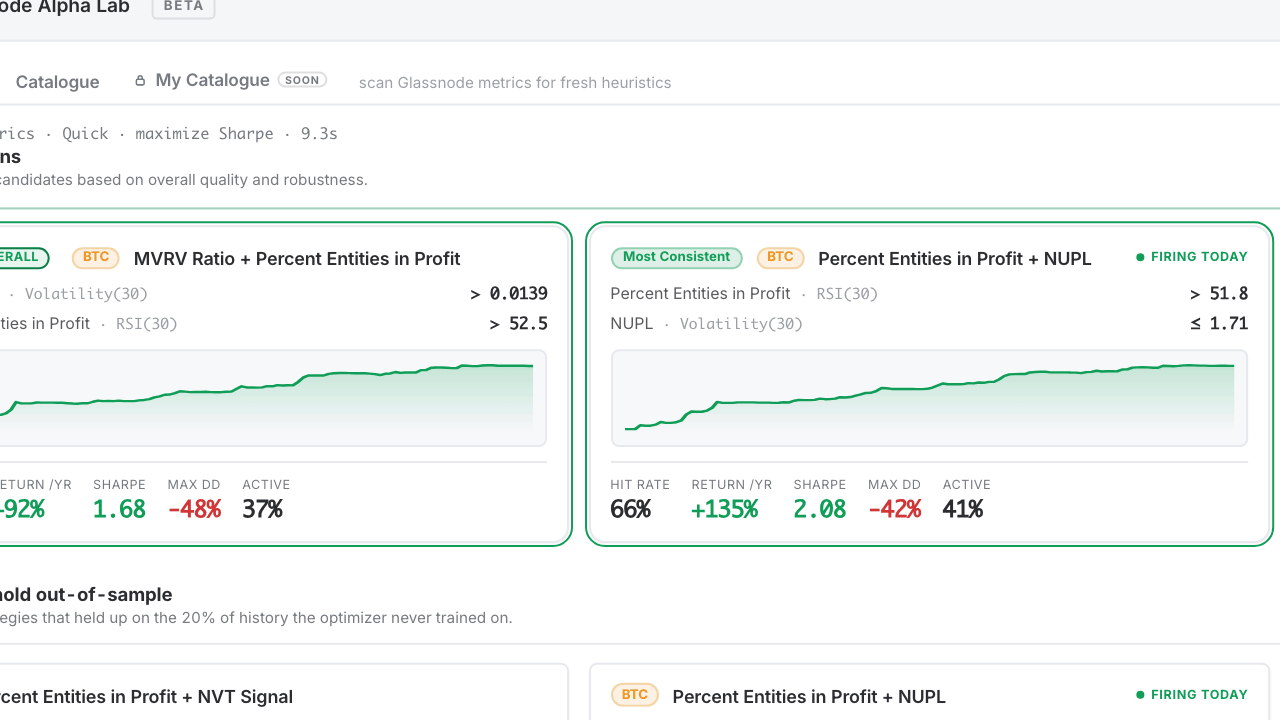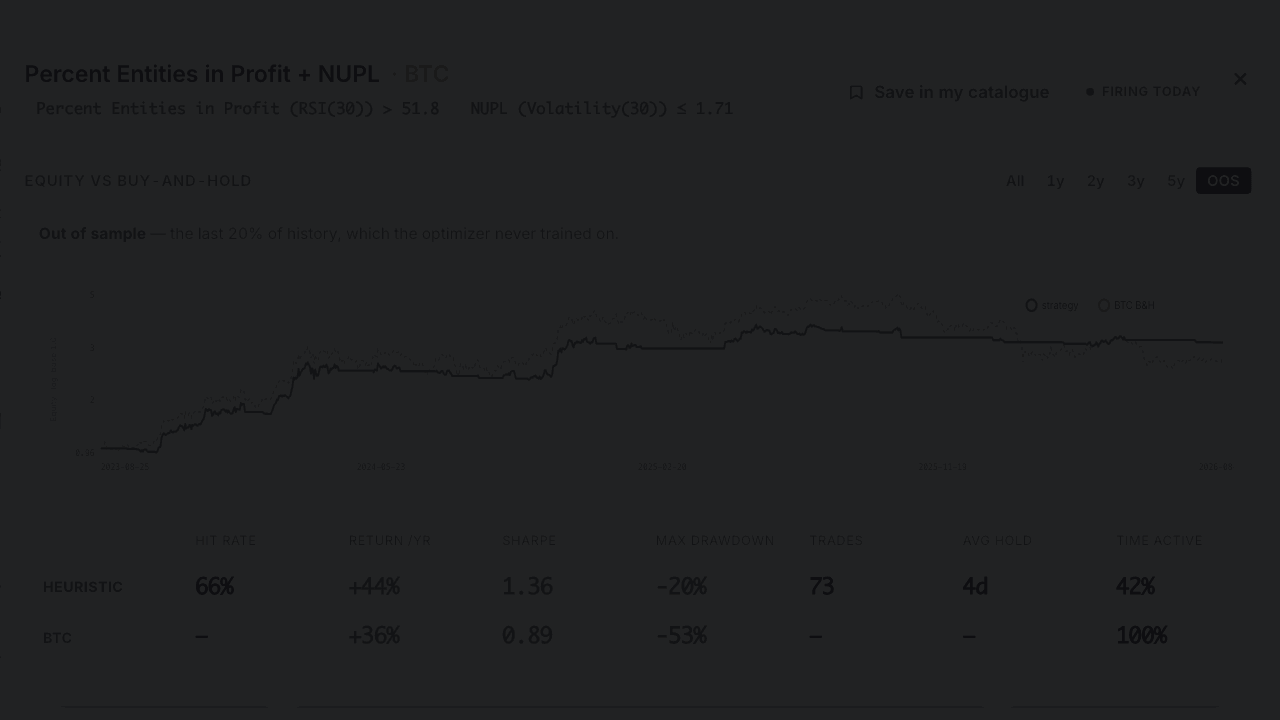
Each rule is accompanied by the evidence needed to evaluate it, including historical return, Sharpe ratio, maximum drawdown, hit rate, trading frequency and an equity curve. Users can compare the rule with the underlying asset, inspect different time horizons and see whether its conditions are firing on the latest available data. It helps surface promising relationships while keeping the underlying logic visible.
Three ways to research
Different investors want different levels of control. The product provides three ways into the same research engine.
Easy mode: Go from a question to ranked heuristics
Easy mode is designed for speed and accessibility. Choose an asset, select whether you want to investigate buying or short opportunities, pick the metrics to scan and set the search effort. Alpha Lab runs the workflow above in the background and returns the most promising rules as readable signal cards — viewable as metric pairs or decomposed into single-metric rules, and filterable to an investor's preferences, for example drawdown, risk-adjusted return, hit rate or a particular evaluation period.
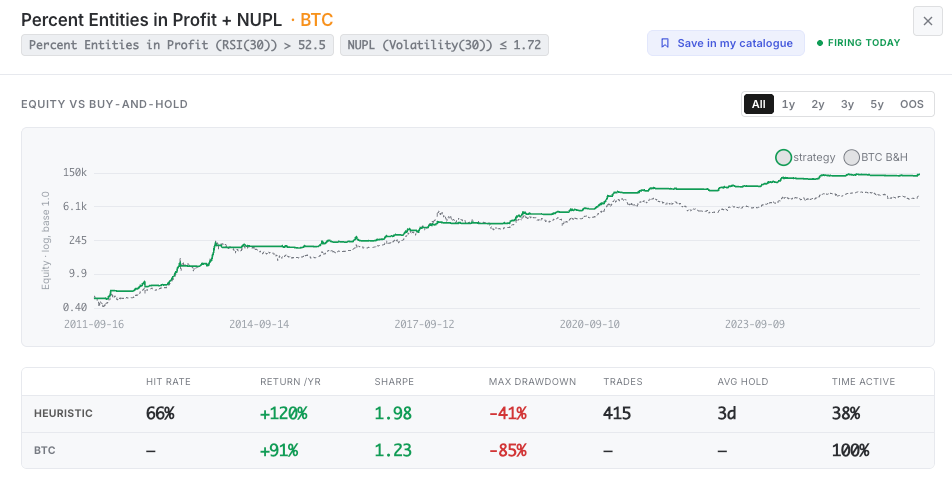
The workflow is iterative by design. Users can refine the metric set, rerun the search and compare the new results with previous attempts. That turns a one-off screen into a structured discovery loop: form a hypothesis, test it, learn from the result and narrow the search.
Advanced mode: Inspect every step
Advanced mode exposes all the steps behind the search. Users can control the feature space by selecting both the source metrics and the transformations applied to them, including z-scores, RSI, moving averages, volatility and percentile-based features. Transformation windows can be adjusted to test how the same underlying metric behaves across different horizons.
They can also define what the model should learn. The research application includes default labelling for long and short opportunities, but users can paint custom zones directly onto the price history.
This opens the door to more specific questions:
- Which metrics have historically characterized local bottoms?
- What tends to appear near market tops?
- Which features are associated with a volatility regime or a parabolic move?
Once the search is complete, Advanced mode shows the path from model to rule. Users can compare machine-learning models, inspect feature influence, review the full heuristic table and analyze individual rules in detail.
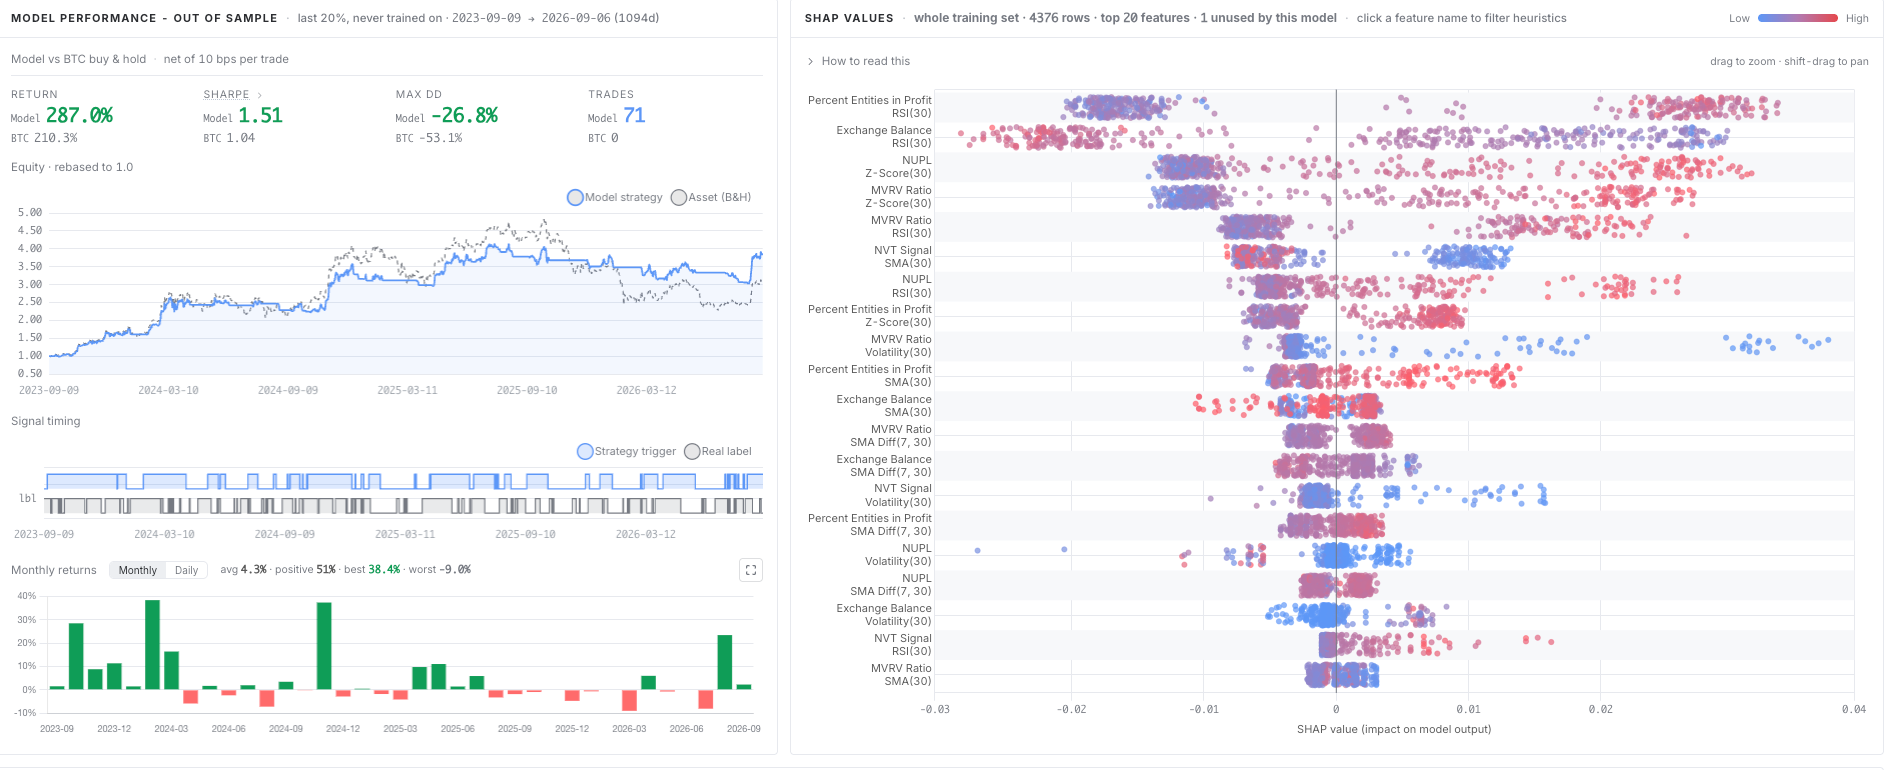
The platform also supports stress-testing of heuristic. If a result only works at one exact threshold or lookback window, that is a warning sign. A more credible relationship should remain reasonably stable when nearby parameters change.
Alpha Lab makes that sensitivity visible, helping researchers distinguish a potentially durable pattern from a finely tuned historical accident.
Agents mode: Put Autoresearch to work
Some research questions are better treated as a loop than as a single query.
Through Alpha Lab’s MCP server, compatible AI agents can access the same metric catalogue and optimization engine as the human interface.
An investor can give an agent a research objective, such as exploring groups of metrics until it finds a rule that improves risk-adjusted performance relative to a benchmark and let it run, evaluate and refine successive searches.
This is a natural use case for agentic research. The objective can be defined, the outcome can be measured, and every candidate can be checked against a consistent evaluation framework.
The agent handles the repetition; the investor retains control of the question, assumptions and final judgment. The strongest findings can then be handed back to the visual interface for deeper inspection or saved into a working catalogue.
From discovery to a living catalogue
Alpha Lab’s Catalogue contains strategies that have already been identified and saved by the Glassnode team. Users can browse by asset, direction and risk or performance characteristics, then study how a rule behaved across its full history, out-of-sample period and live window after it was catalogued.
Investors can also save relevant findings to My Catalogue, creating a focused research universe for their own team.
Over time, that working set becomes more than a list of backtests. The platform can surface rules whose recent behavior has weakened, flag overlapping strategies, and help identify gaps in coverage. It also benefits from a Lindy effect: the longer a strategy continues to perform in a live trading environment, on data it has never seen before, the greater the confidence that its behavior is robust rather than a product of overfitting.
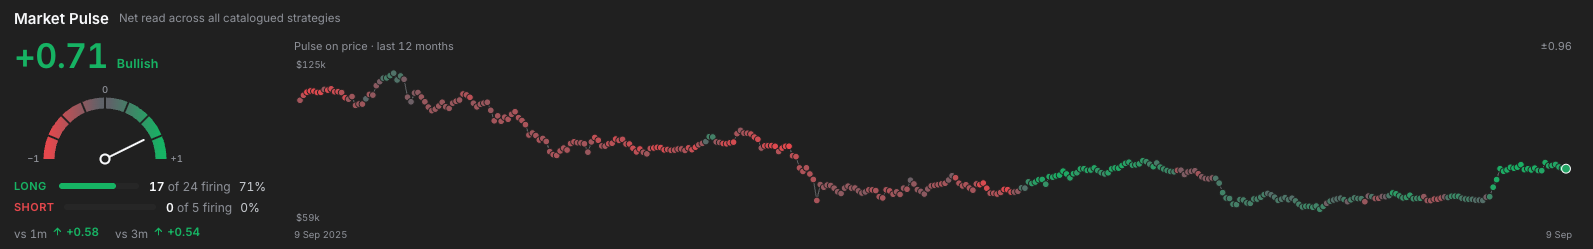
The Market Pulse provides another view of the same research base. It aggregates which catalogued long and short rules are currently active, offering a compact read of how the selected body of evidence is leaning—while preserving the ability to inspect the individual rules behind that view.
Together, these features connect discovery with ongoing monitoring. The question shifts from “Did this work historically?” to “Is it still behaving as expected?”
A research process built on sound methodology
Alpha Lab follows robust quantitative-research practices designed to reduce overfitting and test whether a result generalizes beyond the data used to discover it. The methodology builds on proprietary research workflows developed at Glassnode for the Bitcoin Sharpe Signal, informed by more than three years of live track record.
The search is a random forest run over a fixed budget of trials. Tree depth stays capped at two, which limits complexity and keeps each rule readable as two conditions.
Validation runs in three stages. Walk-forward validation trains models on earlier data and evaluates them on later periods, preserving the chronological order of the market.
An out-of-sample holdout reserves the most recent 20% of history, excluded from the search and used only for independent evaluation.
Once a rule is catalogued, live evaluation tracks it on newly arriving data that could not have influenced its selection.
Reported performance is net: return and Sharpe ratio both include slippage assumptions.
Together, shallow models, walk-forward analysis, out-of-sample testing, parameter-sensitivity checks and live monitoring help distinguish potentially stable relationships from overfitted historical results. They do not guarantee future performance, but they provide a more disciplined foundation for evaluating each heuristic.
Who Alpha Lab is for
Alpha Lab is built for investors who believe Glassnode data can strengthen their process but want a faster path from exploration to evidence.
For discretionary investors, the product can reveal which metrics and thresholds deserve attention before a market decision.
For quantitative researchers, it provides a configurable environment for feature discovery, model comparison and robustness testing.
For teams experimenting with AI agents, the platform offers a measurable autoresearch loop grounded in the same data and evaluation framework used by the human interface.
The modes are different, but the purpose is the same: make Glassnode’s data easier to turn into research that is focused, transparent and actionable.
Join the beta
Glassnode Alpha Lab is currently available in beta to a limited group of clients. We are looking for research teams and investors who want to test the product against real workflows and help shape what comes next.
If you would like early access, speak with your Glassnode representative or contact the team to join the beta.
Alpha Lab is a research product. Its outputs are based on historical data and do not constitute investment advice or a guarantee of future performance.
